
That’s the short version. Now let’s actually walk through it properly, because getting the number right matters more than getting it fast.
Table of Contents
ToggleWhat Is Net Worth? (And Why It’s the One Number That Matters)
Most people track their salary. Very few track their net worth. That’s a problem, because salary tells you how much money passes through your hands, while net worth tells you how much of it actually stuck.
In simple terms, net worth is what you own minus what you owe. If you sold everything you have today, paid off every loan and every rupee of debt, whatever’s left over is your net worth. Understanding your personal net worth is the starting point for every financial planning decision you’ll make, whether that’s buying a house, planning a wedding, or just getting your savings on track. It doesn’t matter if you earn 40,000 a month or 4 lakh a month. What matters is the gap between what you’ve accumulated and what you still owe.
At BusinessMust, we talk to a lot of salaried professionals, freelancers, business owners, and married couples trying to get a handle on their finances, and almost everyone assumes a high salary automatically means a healthy net worth. It doesn’t. A person earning 15 lakh a year with heavy EMIs and no savings can easily have a lower net worth than someone earning half that who invests consistently and avoids unnecessary debt.
That’s exactly why learning how to calculate net worth is one of the first things you should do before you set any financial goal, whether that’s saving for your kid’s education or just figuring out if you’re on track for retirement.
The Net Worth Formula (Explained Simply)
Now that you know the basics, let’s break down how to calculate net worth step by step. Here’s the formula, stripped of jargon:
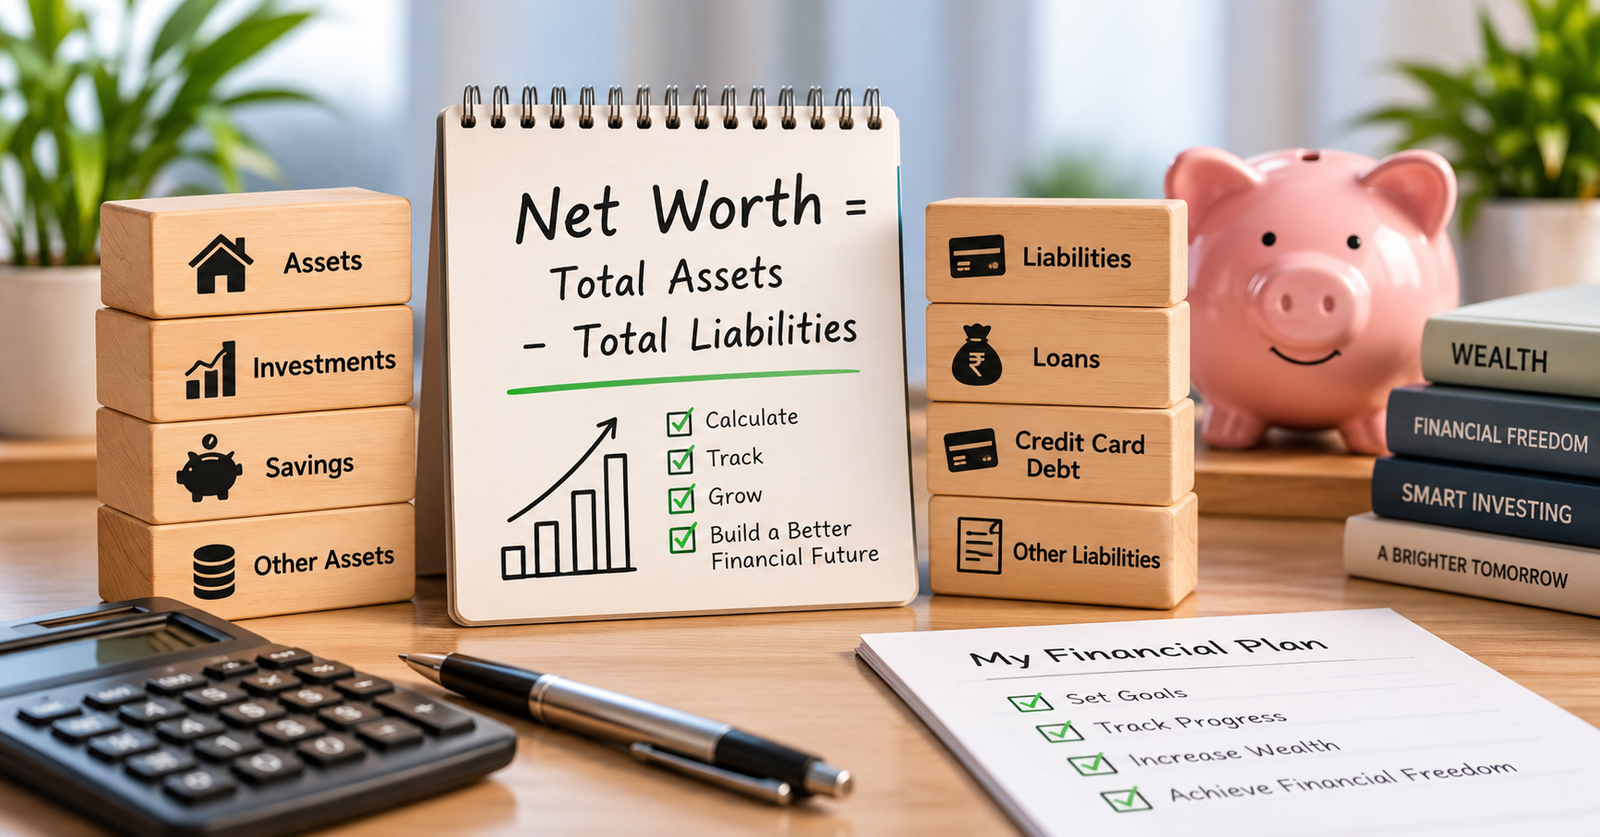
Net Worth = Assets − Liabilities
Assets are things you own that have monetary value. Liabilities are things you owe money on. Subtract one from the other and you get your net worth.
A quick clarification that trips up a lot of beginners: your income and your expenses don’t directly go into this formula. Your salary isn’t an asset. Your monthly grocery bill isn’t a liability. What matters is what those income and expenses have translated into over time, meaning the savings, investments, and property you’ve built up, versus the debts you’re still carrying.
Also worth remembering, net worth is a snapshot, not a trend. It tells you where you stand on one particular day. To actually understand how you’re doing financially, you need to calculate it more than once and watch the direction it moves in. We’ll get to that a bit later.
Step 1: List All Your Assets (What You Own)
The first real step in how to calculate net worth correctly is listing every asset you own, accurately. This is where most people either underestimate or overestimate their wealth, usually because they either forget things or price them wrong. Here’s a practical checklist for an Indian household or individual.
Liquid assets
- Cash in hand
- Savings account balance
- Fixed deposits (FDs)
Investments
- SIP investing for beginners — mutual funds, current value, not what you invested
- Direct stocks (current market price)
- PPF balance
- EPF balance — check your latest passbook, not your offer letter figure
- NPS corpus, per your NPS Trust account statement
- Digital gold vs physical gold, valued at today’s rate, not purchase price
Real estate
- Your primary home, at current market value, not the price you bought it for
- Any other property or land you own
Retirement and insurance
- Employer pension value, if applicable
- Surrender value of any life insurance policy that has an investment component (not term insurance, since that has no cash value)
Business assets (for business owners and freelancers)
- Equipment, inventory, and receivables
- Estimated business equity or valuation, if you have one
Vehicles and other valuables
- Car or bike, at current resale value, not purchase price
- Any other valuables like art or collectibles you could realistically sell
A quick but important note on valuation. A lot of people accidentally inflate their net worth by using the price they originally paid for their home or gold instead of today’s market value. If you bought a flat for 60 lakh eight years ago and it’s worth 95 lakh today, use 95 lakh. If your gold is old jewellery, price it at today’s gold rate minus making charges, since you won’t recover those if you sell.
And a quick callout on what does not count as an asset. Your salary is not an asset. Your expected annual bonus is not an asset until it actually lands in your account. Anything you don’t legally own, even if you use it regularly, doesn’t belong here either.
Step 2: List All Your Liabilities (What You Owe)
Now flip to the other side of the ledger. This step is where people tend to forget the small stuff, and the small stuff adds up.
- Home loan or mortgage outstanding balance (not the original loan amount, the amount you still owe today)
- Personal loans
- Car loans
- Education loans
- How to pay off credit card debt faster — outstanding balance, not just the minimum due
- Business loans, if you run a business
- Informal loans, meaning money borrowed from family or friends that you’re expected to repay
- Contingent liabilities, such as a loan you’ve guaranteed for someone else, or pending tax dues
The most common mistake here is using the original loan amount instead of the current outstanding balance. If you took a 30 lakh home loan five years ago and you’ve paid down 8 lakh of principal since then, your liability for this calculation is 22 lakh, not 30 lakh.
Here’s a quick-reference checklist covering both sides at a glance:
| Assets (What You Own) | Liabilities (What You Owe) |
|---|---|
| Cash in hand | Home loan / mortgage outstanding |
| Savings account balance | Car loan outstanding |
| Fixed deposits (FDs) | Personal loan outstanding |
| Mutual funds (current value) | Education loan outstanding |
| Direct stocks (current price) | Credit card outstanding balance |
| PPF balance | Business loan outstanding |
| EPF balance | Informal loans (family/friends) |
| NPS corpus | Contingent liabilities (guaranteed loans, pending tax dues) |
| Gold (physical + digital, today’s rate) | |
| Primary home (current market value) | |
| Other property/land | |
| Employer pension / insurance surrender value | |
| Business equipment, inventory, receivables | |
| Vehicles (resale value) | |
| Other valuables (art, collectibles) |
Step 3: Calculate Your Net Worth (With a Worked Example)
Here’s exactly how to calculate net worth using two real, worked examples, because formulas only click once you see them applied to a real situation.
Example 1: Salaried professional, age 32
Assets:
- Savings account: 1,50,000
- Fixed deposit: 2,00,000
- Mutual funds: 4,50,000
- EPF balance: 3,80,000
- Gold: 1,20,000
- Car (resale value): 3,00,000
- Home (current market value): 65,00,000
Total assets: 81,00,000
Liabilities:
- Home loan outstanding: 42,00,000
- Car loan outstanding: 1,20,000
- Credit card dues: 25,000
Total liabilities: 43,45,000
Net worth = 81,00,000 − 43,45,000 = 37,55,000
Notice something important here. This person’s home is by far their biggest asset, but it’s also tied to their biggest liability. Their actual net worth is a lot smaller than their home value alone would suggest, which is exactly why calculating it properly matters more than just eyeballing your bank balance or your property value. If you want to map out your own numbers the same way, BusinessMust’s budgeting guide for salaried professionals walks through how to organize this month to month.
Example 2: Freelancer/small business owner, age 29
Assets:
- Savings account: 80,000
- Mutual funds: 1,60,000
- Business equipment and receivables: 2,50,000
- Gold: 40,000
Total assets: 5,30,000
Liabilities:
- Business loan outstanding: 1,80,000
- Credit card dues: 40,000
Total liabilities: 2,20,000
Net worth = 5,30,000 − 2,20,000 = 3,10,000
Different life stage, different asset mix, but the same formula applies to both. Here’s how the two compare side by side:
| Salaried Professional (Age 32) | Freelancer / Business Owner (Age 29) | |
|---|---|---|
| Total Assets | 81,00,000 | 5,30,000 |
| Total Liabilities | 43,45,000 | 2,20,000 |
| Net Worth | 37,55,000 | 3,10,000 |
| Biggest asset | Home (65,00,000) | Business equipment & receivables (2,50,000) |
| Biggest liability | Home loan (42,00,000) | Business loan (1,80,000) |
| Key takeaway | High net worth on paper, but largely illiquid (tied up in home equity) | Lower net worth, but more liquid relative to total assets |
This is really the core of how to calculate net worth in practice, list everything out honestly, value it correctly, and do the subtraction.
Common Mistakes to Avoid When Calculating Net Worth
A few errors show up again and again, so it’s worth flagging them directly.
- Using purchase price instead of current value. This is the single most common mistake, especially with property and gold.
- Counting salary or income as an asset. Income is not wealth until it’s been saved or invested.
- Forgetting small liabilities. Credit card dues and informal family loans get left out more often than you’d think.
- Ignoring tax liability on retirement withdrawals. Some of your EPF or NPS corpus may be taxable when withdrawn, per current Income Tax Department rules, which technically reduces its real value.
- Double-counting jointly owned assets with a spouse. If you and your partner are calculating household net worth together, make sure joint assets aren’t counted twice.
- Ignoring depreciation on vehicles. Your car is worth less every year. Use resale value, not purchase price.
Net Worth vs. Liquid Net Worth (Why the Difference Matters)
Here’s something almost nobody talks about, but it matters a lot in real life. Total net worth and liquid net worth are not the same thing.
Liquid net worth is the portion of your net worth you could actually access in cash within about 30 days, minus your liabilities. It excludes things like your home, EPF (which has withdrawal restrictions), and business equity, which can’t be converted to cash quickly.
Take the salaried professional from Example 1. Their total net worth was 37,55,000, but most of that is locked in home equity and EPF. Their actual liquid net worth, meaning savings plus FD plus mutual funds minus short-term liabilities, is closer to 8,00,000.
| Net Worth | Liquid Net Worth | |
|---|---|---|
| Definition | Total assets minus total liabilities | Cash-convertible assets (within ~30 days) minus liabilities |
| Includes | Home, EPF, business equity, all investments | Savings, FDs, mutual funds, liquid stocks |
| Excludes | Nothing (full picture) | Home equity, EPF, business equity, illiquid assets |
| Example (from Example 1) | 37,55,000 | ~8,00,000 |
| Best used for | Long-term financial planning, tracking wealth growth | Emergency planning, short-term financial flexibility |
This distinction matters enormously for emergency planning. A high net worth on paper doesn’t help you if your car breaks down or you lose your job next month and most of your wealth is sitting in illiquid assets. If you’re not sure where you stand on this front, BusinessMust’s guide on how much emergency fund do you actually need is a good next read. Knowing both numbers, not just one, gives you a much more accurate picture of your actual financial flexibility.
Average Net Worth by Age in India (Where Do You Stand?)
India doesn’t have the same granular net worth survey data that countries like the US or Canada publish regularly, so exact benchmarks are harder to pin down and vary a lot by city, income level, and data source. For broader household financial data, sources like the Ministry of Statistics and Programme Implementation are a reasonable reference point, though they track household finances more broadly rather than individual net worth. That said, directionally, net worth tends to climb with age as EPF balances grow, home loans get paid down, and investments compound.
| Age Bracket | Typical Financial Stage | What to Focus On |
|---|---|---|
| 18–25 | Often zero or negative net worth (education loans, early career) | Build an emergency fund, start a small SIP, avoid high-interest debt |
| 26–35 | Net worth starts climbing (EPF, first investments, possibly a home loan) | Increase savings rate, automate SIPs, avoid lifestyle inflation |
| 36–45 | Home equity grows, EPF/NPS corpus builds meaningfully | Diversify investments, review insurance cover, accelerate loan prepayment |
| 46–55 | Peak earning years, net worth typically highest growth phase | Maximize retirement contributions, reduce high-risk exposure gradually |
| 56+ | Net worth stabilizes or is drawn down toward retirement | Shift to liquid/low-risk assets, plan withdrawal strategy |
Note: India lacks standardized public net worth survey data by age, so treat this as directional, not exact.
Rather than fixating on a number that may not reflect your specific city or income bracket, it’s more useful to treat these benchmarks as a rough compass, not a scorecard. If you’re in your 20s and your net worth is still low or even negative because of education loans, that’s completely normal. If you’re in your 40s and your investments have barely grown beyond your EPF, that’s a signal to look at your savings rate and asset allocation, not a reason to panic. BusinessMust’s retirement planning calculator can help you work out what you’ll actually need by the time you get there.
The real value of this exercise isn’t comparing yourself to a national average. It’s comparing yourself to where you were a year ago.
How Often Should You Calculate Your Net Worth?
Quarterly or twice a year is the sweet spot for most people. Monthly tracking often creates unnecessary anxiety over short-term market fluctuations that don’t actually reflect your long-term progress, and daily tracking is honestly a waste of time for anyone who isn’t a full-time trader.
A simple spreadsheet works perfectly well for this. List your assets and liabilities in two columns, update the numbers every quarter, and track the trend line over time. The direction your net worth is moving in matters far more than the exact number on any single day.
How to Increase Your Net Worth (Practical Steps)
Once you know how to calculate net worth, the next logical question is how to grow it. There are really only three levers that move this number.
Increase your savings rate. The gap between what you earn and what you spend is what actually builds your net worth over time. Even moving from a 10% to a 20% savings rate compounds significantly over a decade.
Invest consistently. Cash sitting idle barely keeps up with inflation. A free SIP calculator can show you how small, regular investments into diversified mutual funds or index funds turn savings into real growth instead of stagnation.
Pay down high-interest liabilities first. Every rupee of credit card or personal loan debt you clear is a guaranteed, risk-free improvement to your net worth, often a better return than most investments given how high those interest rates typically are. Use a loan EMI calculator to see exactly how much faster you can close out a loan with small extra payments.
A few audience-specific notes worth adding here. If you’re a salaried professional, automating your SIPs right after payday removes the temptation to spend first and save later. If you run a business, keep your personal and business net worth tracked separately so one doesn’t distort your view of the other. If you’re a freelancer with irregular income, build a cash buffer before you invest aggressively, since inconsistent income makes you more vulnerable to forced withdrawals at the wrong time. And if you’re managing finances as a couple, track your household net worth jointly so neither partner has a blind spot around shared liabilities.
What If Your Net Worth Is Negative?
If you just did this calculation and landed on a negative number, take a breath. It’s genuinely common, especially for students, recent graduates, and anyone early into a large loan like a home or education loan.
A negative net worth isn’t a failure. It’s a starting line. What actually matters is what you do next.
Track it anyway, even if it’s negative, so you have a baseline to measure progress against. Prioritize paying down your highest-interest debt first, since that’s usually what’s dragging the number down fastest. BusinessMust’s guide on the debt snowball vs avalanche method breaks down which approach fits your situation better. And avoid taking on new liabilities until your existing ones are under control. Small, consistent progress from a negative number is still progress.
FAQs
How do you calculate net worth step by step?
Does net worth include salary or income?
Is net worth the same as savings?
Should I include my home in net worth calculations?
What is a good net worth for my age in India?
How is net worth different for a business owner vs. a salaried employee?
Final Note
Now that you know how to calculate net worth, the next step is tracking it consistently. It takes maybe thirty minutes, and it gives you a far clearer picture of your financial reality than your salary slip ever could. Do it once, do it honestly, and then do it again in three months. That’s really all it takes to start making informed decisions about saving, investing, and paying down debt.
Ready to see where you stand? Use BusinessMust’s free net worth calculator to get your number in under 5 minutes, no signup required.
Disclaimer: This article is for general informational and educational purposes only and does not constitute financial, investment, or tax advice. Net worth calculations, benchmarks, and examples provided here are illustrative and may not reflect your specific financial situation. Please consult a qualified financial advisor or chartered accountant before making any financial decisions.
